Is Mold Covered by Homeowners Insurance? What Homeowners Should Know
Mold coverage depends on the individual homeowners insurance policy, the cause of the water or moisture condition, applicable exclusions or endorsements, coverage limits, and the facts surrounding the loss. Independent inspection and moisture documentation can help establish property conditions, but they do not determine whether a claim is covered.
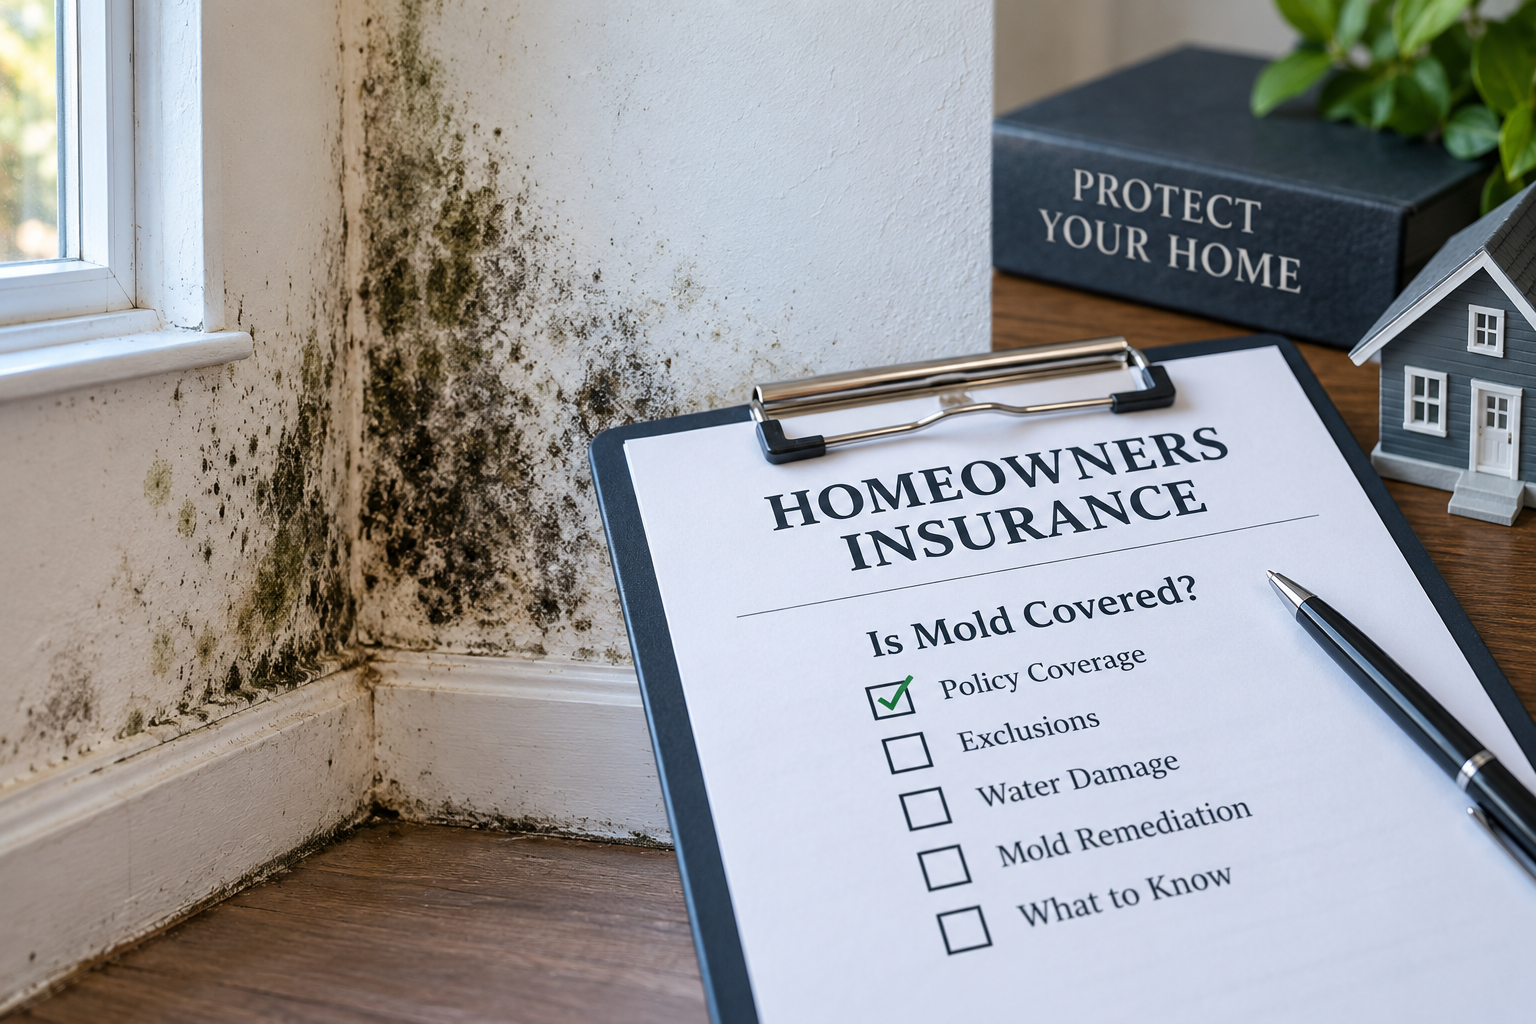
Discovering mold after a leak, plumbing failure, storm, or other water event can quickly raise questions about cleanup, repairs, documentation, and insurance.
One of the most common questions homeowners ask is: Does homeowners insurance cover mold?
There is no single answer that applies to every property or policy. Coverage depends on the language of the individual insurance contract and the circumstances that caused the mold or moisture condition.
Important: This article provides general educational information only. Insurance coverage is determined by the insurance carrier under the specific policy, including its covered perils, exclusions, endorsements, limits, deductibles, conditions, and the facts of the claim. Elite Home & Mold Inspections does not determine insurance coverage and does not provide legal or insurance advice.
Does Homeowners Insurance Cover Mold?
Homeowners insurance policies provide coverage according to the terms of the individual contract.
Some policies may provide limited coverage for mold or fungi under certain circumstances, while others may contain exclusions, sublimits, or endorsements that substantially affect what is covered.
When mold develops after water damage, one of the key questions may be what caused the water or moisture condition in the first place.
A sudden plumbing event, long-term leakage, recurring condensation, foundation seepage, elevated humidity, and exterior flooding may all be treated differently under an insurance policy.
The insurance carrier—not the mold inspector—determines whether a particular loss qualifies for coverage.
Why the Cause of the Water or Moisture Matters
Mold requires moisture to grow.
Because mold is often associated with a water or moisture condition, insurance questions frequently involve both the mold itself and the event that introduced moisture into the building.
Examples of Water Events That May Raise Coverage Questions
Different water events can trigger different sections of a homeowners policy.
Examples that may warrant review with the insurance carrier include:
- A burst plumbing supply line
- A sudden appliance leak
- A leaking water heater
- Storm-related damage to a roof or exterior component
- Water entering after another insured event
- Water damage discovered shortly after a sudden failure
The presence of one of these conditions does not by itself establish coverage.
The insurer evaluates the event under the actual policy and determines whether the cause of loss, resulting damage, mold-related conditions, and associated expenses are covered.
Conditions That May Be Treated Differently by an Insurance Policy
Insurance policies may contain exclusions or limitations involving fungi, mold, repeated seepage, long-term leakage, maintenance-related conditions, flooding, or other sources of moisture.
Examples can include:
- Long-term plumbing leakage
- Repeated seepage
- Ongoing basement moisture
- Foundation water intrusion
- Elevated indoor humidity
- Recurring condensation
- Deferred maintenance
- Surface-water flooding
- Conditions that existed before the reported loss
These examples should not be interpreted as automatic exclusions. The policy and carrier determine how a particular condition is handled.
Can a Policy Have Separate Mold Limits?
Yes. Some homeowners policies may contain separate limits, sublimits, exclusions, or endorsements related to mold, fungi, wet rot, dry rot, remediation, testing, or associated property damage.
The terms and dollar amounts vary by policy.
Homeowners should review their declarations, endorsements, exclusions, definitions, and other policy provisions rather than assuming that a standard mold coverage amount applies.
Questions about the meaning of specific policy language should be directed to the insurance carrier, agent, broker, or another appropriately qualified insurance professional.
Why Documentation Can Matter After Water Damage
Conditions inside a building can change quickly after a water event.
Materials may dry, staining can change, damaged finishes may be removed, and remediation or repair work may begin.
Documentation can help establish what was observed at a particular point in time.
Depending on the situation, useful records may include:
- Photographs and videos
- Dates associated with the water event
- Locations where water or moisture was observed
- Moisture readings
- Inspection findings
- Plumbing or repair documentation
- Invoices and mitigation records
- Laboratory results when mold sampling is performed
Documentation does not create insurance coverage. Photographs, moisture readings, inspection findings, and laboratory results can document property conditions, but the insurance carrier still determines whether those conditions fall within the terms of the policy.
How an Independent Mold Inspection May Help Document Conditions
An independent mold inspection can document accessible property conditions associated with suspected mold, water intrusion, moisture, staining, and affected building materials.
Depending on the property and scope of the inspection, this may include:
- Visual assessment of accessible areas
- Moisture measurements
- Thermal imaging when appropriate
- Photographic documentation
- Observations of water staining or material damage
- Evaluation of accessible affected areas
- Environmental measurements when relevant
- Mold sampling when appropriate
The purpose of the inspection is to document and evaluate property conditions—not to determine whether an insurance policy applies.
Elite Home & Mold Inspections does not perform mold remediation. Keeping inspection and remediation separate allows our inspection and testing role to remain independent from remediation work.
When Might Mold Testing Be Useful?
Mold testing is not automatically necessary after every water event.
Sampling may be useful when laboratory information can help answer a specific question arising from the inspection.
Examples may include:
- Laboratory identification of suspected microbial growth
- Questions involving airborne fungal spores
- Conditions that are not visually clear
- Documentation associated with water-damaged areas
- Additional information needed to support the inspection findings
Professional mold testing may include air or surface sampling depending on the conditions observed and the purpose of the testing.
Laboratory results should be interpreted together with the building observations, moisture conditions, water-event history, and sample locations.
When Can Moisture Mapping Be Useful?
Mold is only one possible concern after a water event.
Building materials can become wet before visible mold develops, and moisture conditions can change significantly as drying progresses.
Independent moisture mapping and water intrusion documentation can help document accessible moisture conditions and affected locations at the time of an inspection.
Depending on the property and event, moisture measurements may involve accessible:
- Walls
- Ceilings
- Flooring
- Trim
- Cabinetry
- Wood building materials
- Other affected areas
Moisture readings document conditions observed during the inspection. They do not determine insurance coverage or establish responsibility for the water event.
Should You Wait Until Mold Appears Before Documenting Water Damage?
Not necessarily.
If building materials are wet following a leak or water event, documenting those conditions may be useful before visible mold develops.
Moisture can affect drywall, plaster, flooring, insulation, wood, cabinetry, ceilings, and other materials even when mold is not immediately visible.
Early documentation may also provide a clearer record of where moisture was identified before drying, demolition, repair, or other work changes the condition of the property.
What Should You Do After Discovering Water Damage?
The appropriate response depends on the source, extent, and circumstances of the water event.
General steps may include:
- Document visible conditions with photographs or video when it is safe to do so.
- Address an active water source when safely possible.
- Contact the insurance carrier promptly if an insurance claim may be involved.
- Ask the carrier what documentation or procedures it requires.
- Take reasonable steps to limit additional property damage when safe and appropriate.
- Retain relevant records, photographs, invoices, reports, and repair information.
- Consider independent mold inspection or moisture documentation when the conditions warrant it.
Homeowners should follow the requirements of their own insurance policy and the instructions provided by their carrier or adjuster.
What About Flood Damage?
External flooding is generally treated differently from many internal water events.
Most standard homeowners insurance policies do not cover flood damage, and separate flood insurance may be needed for damage caused by flooding.
Flood policies also contain their own definitions, exclusions, limits, and requirements.
For that reason, homeowners dealing with flood-related mold or moisture should contact the appropriate insurance carrier directly rather than assuming the same rules apply as they would for a plumbing leak or another type of water event.
Does “Black Mold” Receive Different Insurance Coverage?
The color of suspected mold does not by itself determine insurance coverage.
Many types of fungal growth can appear black, dark green, brown, gray, white, or other colors.
Insurance determinations are based on the policy and facts of the loss—not simply on the color of visible growth.
If laboratory identification would provide useful information for the inspection, targeted mold sampling may be appropriate.
Can a Mold Inspection Guarantee That an Insurance Claim Will Be Approved?
No.
A mold inspector can document conditions observed within the inspection scope, collect samples when appropriate, provide laboratory results, and report inspection findings.
An inspector cannot determine whether the insurance company must pay a claim or guarantee that a claim will be approved.
Inspection and insurance coverage are separate issues. Independent inspection can provide factual documentation about property conditions. The insurance carrier determines whether the reported loss is covered under the applicable policy.
Can Mold Develop After a Water Loss?
Yes. Mold can develop when susceptible materials remain damp long enough for fungal growth to occur.
The conditions following a water event can vary based on factors such as:
- The amount of water involved
- How long materials remained wet
- The type of materials affected
- Indoor temperature
- Relative humidity
- Ventilation and airflow
- Drying conditions
- Whether moisture entered concealed areas
This is one reason documentation of moisture conditions can be useful following a significant water event.
Can Additional Mold or Fungi Coverage Be Available?
Some insurance companies may offer endorsements or other policy options that modify mold, fungi, water-damage, or related coverage.
Availability, limits, exclusions, pricing, and policy language vary by carrier and policy.
Homeowners interested in understanding or changing their coverage should discuss the available options with their licensed insurance agent, broker, or carrier.
Elite Home & Mold Inspections does not recommend insurance products or advise homeowners about which insurance coverage they should purchase.
Mold Inspection & Moisture Documentation in Massachusetts & New Hampshire
Elite Home & Mold Inspections provides independent mold inspections, mold testing, moisture evaluation, and water intrusion documentation for residential and commercial properties throughout Massachusetts and New Hampshire.
Our team has over 30 years of combined experience in the construction and environmental industries.
Depending on the inspection scope, we can document accessible building conditions, collect moisture measurements, perform mold sampling when appropriate, and provide laboratory results and written inspection findings.
We do not perform mold remediation.
Learn more about our mold inspection services, mold testing services, and moisture mapping and water intrusion documentation.
Frequently Asked Questions
Does homeowners insurance cover mold?
It depends on the individual policy and the circumstances that caused the mold or moisture condition. Policies may contain exclusions, endorsements, sublimits, or other provisions affecting mold-related losses. The insurance carrier determines coverage.
Does homeowners insurance cover mold after a burst pipe?
A sudden plumbing failure may be evaluated differently from a long-term or repeated leak, but the presence of a burst pipe does not automatically establish mold coverage. Coverage depends on the policy and circumstances of the claim.
Does homeowners insurance cover black mold?
The color or species of mold does not by itself determine insurance coverage. Coverage depends on the policy terms and facts surrounding the loss.
Is mold caused by flooding covered by homeowners insurance?
Most standard homeowners insurance policies do not cover external flood damage. Flood insurance is generally a separate form of coverage. The specific policy and carrier should be consulted regarding any flood-related loss.
Can a mold inspection help document an insurance claim?
An independent mold inspection can document accessible property conditions, photographs, moisture findings, and laboratory results when sampling is performed. This information may provide a factual record of conditions, but it does not determine whether a claim is covered or approved.
Can moisture mapping be useful after a water loss?
Yes. Moisture mapping can document accessible areas where elevated moisture is identified at the time of the inspection. This can be useful when understanding the extent and location of moisture following a leak or water event.
Should I contact my insurance company before an inspection?
If you believe an insurance claim may be involved, contacting the carrier promptly can help you understand its reporting requirements, documentation expectations, and claim procedures. An independent inspection is separate from the insurance company's coverage determination.
Does Elite determine whether my insurance company has to cover mold?
No. Elite Home & Mold Inspections evaluates and documents property conditions. We do not interpret insurance policies, determine coverage, negotiate claims, or provide legal advice.
Does Elite perform mold remediation?
No. Elite Home & Mold Inspections provides independent mold inspection and testing services and does not perform mold remediation.
References for Further Reading
National Association of Insurance Commissioners — Homeowners Insurance Consumer Information
National Flood Insurance Program — Homeowners Insurance and Flood Coverage
Need Independent Documentation After Water Damage?
Elite Home & Mold Inspections provides independent mold inspections, mold testing, moisture mapping, and water intrusion documentation throughout Massachusetts and New Hampshire. Our role is to document property conditions—not to determine insurance coverage.
Serving Massachusetts & New Hampshire